A savings account is necessary for any business sitting on spare cash. But if you skip the basics, it can cost you.
Low interest, hidden fees, or clunky access rules can quietly eat into your returns. You won’t notice until the damage is already done.
We’ll walk you through choosing the right savings account, covering rates, access, and fees that affect your bottom line. Once you’ve read this, you’ll easily tell account types apart and pick one that fits your goals.
Before opening anything, you need to know what sets a good account apart from an average one. So, let’s start with how a savings account actually works.
What Is a Savings Account and How Does It Work?
A savings account is a bank account built to hold spare funds while paying you interest over time. Unlike everyday spending, this money sits and grows in the background.
Most financial institutions calculate interest daily. Then they pay it into your account monthly, so your balance quietly climbs without any extra effort on your part.

Here’s the useful bit: most savings accounts link to a transaction account. This makes it simple to move funds across whenever you need them, without closing anything down or opening a new account from scratch. The account holder keeps full control the entire time.
Savings Account vs Transaction Account: What’s the Difference?
Mixing up a savings account and a transaction account is an easy mistake. And it can quietly cost you interest.
Here’s a quick side-by-side to clear it up.
| Feature | Savings Account | Transaction Account |
| Purpose | Grows spare funds | Handles daily spending |
| Interest | Usually higher | Usually low or none |
| Withdrawals | Often limited | Unlimited |
| Access | Online banking, linked account | Cards, direct debits, ATM withdrawals |
A transaction account covers the everyday stuff, groceries, bills, direct debits, while a savings account builds up in the background. Most banks pair the two through a linked transaction account, so you can shift money across without closing either one.
For instance, Judo Bank lets you link your savings account to an existing transaction account at any other bank. It ultimately gives you the same easy transfers without needing two accounts in one place.
How to Compare Savings Accounts Before You Choose One
Comparing a few key factors upfront saves you from switching banks down the track. These are the ones worth checking first.

Interest Rates vs Bonus Rates: What’s the Real Difference?
Savings account interest rates vary widely between banks, so it pays to compare before you commit. A bonus interest rate only applies once you meet certain bonus interest criteria, like a minimum monthly deposit or no withdrawals that calendar month. Once you hit those targets, you’ll earn bonus interest well above the base rate.
But if you miss just one condition, though, your rate quietly drops back to the variable interest rate on offer. The Reserve Bank’s official cash rate also shifts these figures over time. So a competitive rate today might not hold twelve months from now.
Choosing Between a Term Deposit and an SMSF Savings Account
Term deposits lock your funds away for a fixed period, in exchange for a set, guaranteed return. That trade-off suits businesses that won’t need the cash anytime soon. SMSF savings accounts work differently, built for self-managed super fund trustees who need to keep retirement savings compliant.
However, your financial situation decides which path makes sense here. If instant access is more important than a locked-in rate, skip the term deposit altogether. But if you’re managing an SMSF, check the eligibility criteria before you apply, as not every provider accepts every fund structure.
How Many Savings Accounts Does Your Business Actually Need?
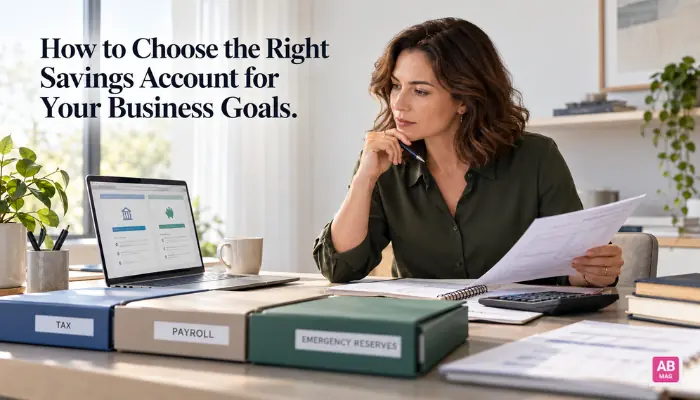
Plenty of businesses split their cash across two or three savings accounts, one for tax, one for payroll, and one for emergencies. This approach stops you from accidentally spending money that’s already earmarked. Rates and fees shift constantly, so it’s worth weighing up a few providers before settling.
If you’re after a high-interest savings account with instant access savings and no lock-in, Judo Bank’s savings account is worth a look as your first savings account or an addition to an existing setup. Still, too many accounts get hard to track. So keep your structure simple and purposeful.
What Else You Should Know Before Signing Up
Now that you know how to compare accounts, a few extra details are worth knowing before you sign up. Account fees catch plenty of people out, so check for a monthly account fee tied to falling below a minimum balance.

Most authorised deposit-taking institutions, including credit unions and building societies, sit under the government’s financial claims scheme. This protects up to $250,000 per account holder in the unlikely event something goes wrong. You’ll also need your tax file number on hand, since banks ask for it when you open an account.
Double-check whether the rate on offer is a variable intro rate or ongoing, since variable interest rates apply differently once the honeymoon period ends. Some providers even let you link Google Pay for quick transfers on the go.
Your Next Move: Picking a Savings Account That Works as Hard as You Do
Choosing a savings account doesn’t need to feel complicated once you know what to compare. Focus on the essentials:
- Interest rates and bonus conditions
- Account fees and minimum balances
- Access rules and linked transaction options
A linked account keeps your everyday spending separate from your business savings, which makes tracking everything far simpler. Running the numbers through a savings calculator beforehand can show you exactly how much more interest you’d earn over a year.
A little research now beats switching accounts later and losing interest along the way. Compare savings accounts properly, and Judo Bank’s offering is a solid one to start with.
Disclaimer: This post is for general information purposes only and does not constitute personal financial advice. Everyone’s financial circumstances, needs and goals are different. Please do your own research and consider speaking with a qualified financial adviser before making any financial decisions.